For anyone comparing Medicare Supplements
Plan G vs. High Deductible Plan G, side by side
Medicare is confusing, and that is exactly why I am here. These two plans pay the same claims. The only real difference is who writes the first check. Here they are, with 2026 numbers.
See What It Would Cost YouOr call me directly at (314) 724-6590.
Same coverage. The difference is who pays first.
Both of these are Medicare Supplement plans, and both are standardized by Medicare. Plan G is Plan G, whichever company sells it.
With regular Plan G, you pay the Part B deductible, which is $283 in 2026. After that the plan picks up your share and you pay nothing more for the year.
With High Deductible Plan G, you pay that same $283 first. Then you keep paying your 20% share until you have paid $2,950 in 2026. Past that line it behaves exactly like Plan G.
You are not buying less coverage. You are funding the first few thousand dollars yourself and keeping the premium difference.
The two plans, with 2026 numbers
| Plan G | High Deductible Plan G | |
|---|---|---|
| Part B deductible | $283 | $283 |
| What you pay after that | Nothing | Your 20% share plus the hospital deductible, until you reach $2,950 |
| Most you pay in one year | $283 | $2,950 |
| Monthly premium, age 65 | $355 men $309 women |
$70 men $61 women |
| If you live with a spouse | 12% lower | 12% lower |
United World Life (a Mutual of Omaha company) 2026 rates for the St. Louis-area ZIP codes, non-tobacco. Your age, ZIP code and health history move these numbers, so I will pull your actual quote.
That gap is about $285 a month for a man and about $248 for a woman. That is roughly $3,000 to $3,400 a year that stays in your pocket, whether you use care or not.
What the $2,950 actually means
- It is set by Medicare, not by the insurance company. The same figure applies to the high-deductible versions of Plans F, G and J, and it changes each year.
- Your $283 Part B deductible counts toward it. You are not paying twice.
- You pay it as you go, only as you use care. Nobody hands you a bill in January.
- Once you reach it, the plan pays what Plan G pays for the rest of the year.
- It resets every January 1. A healthy year means it simply expires unused.
What people do with the savings
Some people keep it. Others use part of it to cover the one thing a supplement does not: the cash cost of a big event.
That is what hospital indemnity, cancer, and heart attack and stroke policies do. They pay you cash when something happens. They are separate policies, not Medicare plans, and they are optional.
The idea is simple. Let the low-premium supplement handle the medical bills, and let a small fixed-benefit policy cover the deductible if a bad year arrives.
And if you would rather not think about any of that, regular Plan G is a perfectly good answer. Simple has real value.
Which one fits you
Most predictable
Regular Plan G
- Around $355 a month at 65
- You pay $283, then you are done for the year
- Very little ever comes out of your pocket
Good fit if you want the fewest surprises and would rather pay monthly than ever see a large bill.
Lowest premium
High Deductible Plan G
- Around $70 a month at 65
- You cover the first $2,950 yourself
- You still come out ahead in a bad year
Good fit if you are healthy, you have savings set aside, and you would rather keep the difference.
How it works when we talk
- You tell me your doctors, prescriptions, age and ZIP code. That is the whole intake. No health questions for this part.
- I run the numbers where you live. Plan G, High Deductible Plan G and Plan N, with what each one really costs in a bad year.
- You decide, or you sleep on it. If it is not the right time, we do nothing. That is a fine outcome too.
If that sounds like the right way to do this, pick a time for a 20-minute conversation — in person at my Ellisville office, by phone, or on Zoom. No cost, no pressure, and no plan pitch.
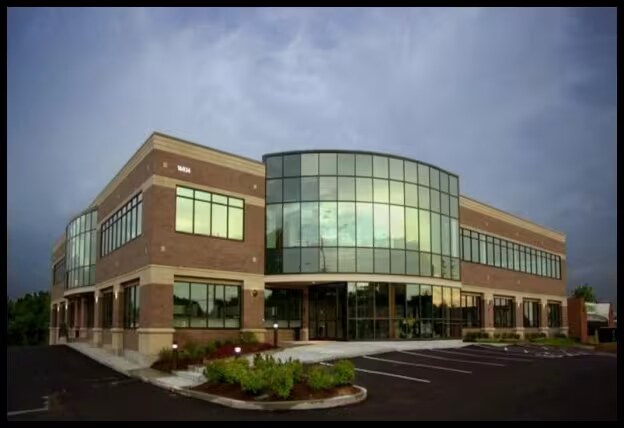
Why people call me instead of a 1-800 number
Independent and local
I am not tied to one carrier, and I am not a call center. You get one agent in Ellisville who answers the phone next year too.
Free to you
No charge for the conversation, the comparison or the help afterward. Carriers pay the same either way, so the guidance costs you nothing extra.
Proven
BBB accredited, 5.0 stars on 88 Google reviews. Most of my clients come from someone they know. Read the reviews.
Let’s put your real numbers next to this
Bring your doctors, prescriptions, age and ZIP code. I will show what Plan G and High Deductible Plan G cost where you live, and what each one does in a bad year.
Book a Free Medicare ConversationOnce you book, I will send you a short, secure form so I can look at your doctors and prescriptions before we talk. Prefer to talk first? Call me directly at (314) 724-6590.
To choosing the plan that fits your life, not the one with the biggest premium.
Marc Mantia
Independent Agent | Review Medicare Benefits, LLC
Office: (636) 203-5840 | Mobile: (314) 724-6590
marc@reviewmedicarebenefits.com
16024 Manchester Rd, Ste 200, Ellisville, MO 63011
P.S. Getting expert help with Medicare doesn’t cost you anything extra. Going without it might.